No. 05
September 2026
Building under pressure
Housing, construction and financing in a market under pressure.
Ama Grupo Imobiliário®
Building under pressure
Housing, construction and financing in a market under pressure.
Editorial Note
Building housing has become an exercise in successive trade-offs. Demand remains high, lending continues to grow and prices maintain an upward trajectory. At the same time, the number of buildings licensed and completed is falling, refurbishment is losing momentum, and labour and material costs remain above the levels recorded a year earlier.
This edition examines these tensions without reducing the problem to a single indicator. Supply depends on the ability to turn planning, financing and projects into completed construction. Affordability depends on the purchase price as well as borrowing costs, location and construction quality. Sustainability, in turn, is beginning to inform routine decisions about insulation, energy and materials.
In Lisbon and on the South Bank, municipal affordable rental programmes provide concrete responses, although they remain limited in relation to the scale of demand. At national level, the conclusion of the PRR housing cycle represents a significant scale of public intervention, but it does not eliminate the need for continuity. Building under pressure therefore means increasing supply without allowing urgency to reduce the quality of buildings, public spaces and the wider territory.
MATTERS / Ama Grupo Imobiliário®
In this issue
- 01ArticleMore capacity, fewer buildings
- 02ArticleCosts did not fall: they merely grew more slowly
- 03ArticleRising house values meet the limit of household income
- 04Article31,700 homes later, the question of continuity begins
- 05ArticleRefurbishment sustains work but loses its project pipeline
- 06ArticleAffordable rent: concrete responses, limited scale
- 07ArticleLow carbon reaches the building site
01 · Article
More capacity, fewer buildings
Construction employs more people and receives more financing, but these signs of activity have yet to translate into equivalent growth in supply. In the second quarter of 2026, both building permits and completions declined.
A sector expanding unevenly
Portugal’s construction sector entered the second quarter of 2026 with 400.4 thousand workers, the highest figure since 2011. Employment in the sector grew by 11.2% compared with the same period a year earlier, outpacing growth across the economy as a whole. Financing also increased: in the first half of the year, new loans for house purchases, excluding renegotiations, reached €12.153 billion. In July, lending to construction and property companies also showed year-on-year growth.
These indicators describe a sector with more people and greater access to finance. They do not, however, mean that more construction is reaching the market. Around 6.2 thousand buildings were licensed in the second quarter of 2026, 7.1% fewer than a year earlier. Completed projects fell by 4.2%. Across the first half of the year, the number of licensed buildings was 8.4% lower than in the corresponding period.
The difference between buildings and dwellings
The figures require a distinction. Despite the reduction in the total number of buildings, the number of dwellings licensed in new family housing developments increased by 10.8% in the second quarter. Completed dwellings rose by 11.6%. It is therefore possible to license fewer buildings while simultaneously creating more housing units — for example, through larger or denser developments.
Even so, this development does not automatically solve the supply problem. Between licensing, procurement, construction and a home actually entering the market lies a period affected by costs, technical capacity, the availability of serviced land and administrative procedures. The rise in employment demonstrates mobilisation capacity, but the decline in licensed buildings points to possible weakness in the future pipeline.
The decisive indicator
For buyers, residents and investors, the central issue is not merely activity in the sector, but the quantity, location, type and price of the homes that become available for use. Construction can grow in terms of employment and financing without producing a proportionate housing response, particularly when part of its capacity is absorbed by infrastructure, public facilities, tourism or residential segments with restricted access.
The second quarter therefore shows an active construction economy, but one in which resources are not being fully converted into supply. Pressure on housing will ease only when increased capacity is consistently reflected in licensed projects, completed construction and homes suited to household incomes and local needs.
Sources
- AICCOPN
- Idealista News
- Instituto Nacional de Estatística (INE)
02 · Article
Costs did not fall: they merely grew more slowly
In July, new housing construction costs increased by 6.8% year on year. Labour rose by 7.3% and materials by 6.3%, maintaining pressure on budgets, contracts and final prices.
An increase across the entire project
New housing construction costs increased by 6.8% in July 2026 compared with the same month a year earlier. The rate was 0.6 percentage points below that recorded in June, but the slowdown does not represent a reduction in costs. It merely means that they continued to rise at a slightly slower pace. Materials increased by 6.3% and labour by 7.3%.
This distinction is relevant when assessing the market. When growth slows, a budget does not return to previous levels. The new cost base remains in place and continues to affect projects still under development, contracts being procured and works whose financial margins were set before prices were updated.
The effect on projects
The increase in labour costs comes in a context of rising employment in the sector. The arrival of more workers improves delivery capacity, but does not eliminate the pressure associated with demand for skills, specialisation and site management. For materials, the increase affects different construction components and requires solutions, suppliers and purchasing schedules to be reviewed.
For developers, this trend may reduce the margin available to absorb unforeseen costs or fund elements that are not strictly mandatory. For designers, it increases the risk of decisions being based solely on initial cost, at the expense of performance over the building’s lifetime. For buyers, some of the pressure may emerge in the sale price, payment terms or reductions in floor area and specification levels.
A response based exclusively on substituting cheaper solutions may create costs later. Less insulation, systems that are complex to maintain or materials with lower durability transfer expenses to the building’s users. Budgetary discipline must therefore distinguish between what can be simplified and what protects comfort, energy efficiency, safety and the home’s capacity to adapt.
Planning for the total cost
The current context reinforces the importance of integrating design, construction and operation from the earliest decisions. Repeating components, modular design, reducing waste, early procurement and selecting locally available materials can limit exposure to fluctuations without reducing quality.
Building under pressure demands even greater precision. Costs must be monitored throughout the entire process, not only when the contract is awarded. The analysis should include maintenance, energy consumption, repairability and the expected lifespan of components. When material and labour costs rise simultaneously, efficiency ceases to be merely a technical option: it becomes a condition for preserving economic viability and the quality of the built environment.
Sources
- Idealista News
- AICCOPN
- Instituto Nacional de Estatística (INE)
03 · Article
Rising house values meet the limit of household income
Advertised house prices increased by 7.5% in August. In July, the median bank valuation reached €2,240 per square metre and the average mortgage payment rose to €414.
Three indicators, the same pressure
The residential market entered late summer with further signs of rising values. In August 2026, the median advertised price of homes for sale in Portugal reached €3,207 per square metre, 7.5% more than a year earlier. The Lisbon Metropolitan Area recorded an annual increase of 5%, below the national average, while the district of Santarém saw one of the highest increases in the country, at 22.9%.
Advertised prices do not necessarily correspond to final transaction values, but they indicate the direction of supply entering the market. Another indicator, based on valuations carried out for lending purposes, confirms the trend. In July, the median bank valuation of housing reached €2,240 per square metre, a year-on-year increase of 15.2%. Around 34.1 thousand valuations were considered.
Financing also weighs heavily
Rising property values coincide with a slight increase in the cost of existing borrowing. The implicit interest rate across all mortgage agreements rose to 3.135% in July. The average payment reached €414, €20 more than in July 2025. For agreements signed in the previous three months, the average payment reached €731, representing a year-on-year increase of 15.1%.
This set of data helps explain why demand may remain active without access becoming easier. A higher bank valuation may make it possible to finance a more expensive purchase, but it also confirms that the asset required to secure the loan is more costly. At the same time, repayments depend on the principal, term, applicable rate, insurance and other charges.
National averages conceal significant territorial differences. In Lisbon, absolute price levels continue to require substantial equity. In the Tagus Valley, faster percentage increases may reduce the relative advantage of areas previously sought as alternatives. Displaced demand does not eliminate pressure: it redistributes it to municipalities where supply, infrastructure and transport may not grow at the same pace.
Affordability as the central measure
Price per square metre is insufficient to assess access to housing. Analysis must relate price, disposable income, the initial deposit, repayments, mobility costs and property quality. A seemingly more affordable home may involve higher energy bills, a need for building work or longer daily journeys.
Rising asset values benefit owners and strengthen bank collateral, but widen the gap for those seeking to enter the market. Without greater diversity of supply — for purchase, rent and intermediate models — the constraint ceases to be the availability of credit and becomes households’ stable capacity to meet the total cost of living in a home.
Sources
- Idealista News
- Instituto Nacional de Estatística (INE)
- Banco de Portugal
04 · Article
31,700 homes later, the question of continuity begins
The Government announced the completion of 31,700 housing solutions funded under the PRR, exceeding the initial target by 5,700. The result concludes a phase of investment, but not the structural problem of supply.
A target exceeded
The deadline for implementing investments and reforms under the Recovery and Resilience Plan ended on 31 August 2026. In the housing component, the Government announced the completion of 31,700 housing solutions, exceeding by 5,700 the initial target of 26 thousand set in 2021. The programme covered solutions aimed at families living in conditions considered inadequate, with the involvement of municipalities and other development bodies.
The figure is significant in the context of Portuguese public housing. It represents financing, procurement and delivery capacity distributed across the country. It also demonstrates that administrative targets can be exceeded when there is a dedicated source of funding, defined deadlines and coordination between different levels of government.
Counting housing solutions is not enough
Physical completion is, however, only part of the outcome. The assessment must consider where the homes are located, how many involve new construction or refurbishment, which types were provided, the maintenance costs and how the new dwellings are integrated into existing neighbourhoods, transport networks and facilities.
A housing solution is not merely an accounting unit. Its performance continues over time through thermal comfort, accessibility, material durability, management of communal areas and the relationship with public space. Accelerated delivery driven by funding deadlines should not dispense with scrutiny of these dimensions.
The Construir Portugal programme also included legislative and administrative measures, including changes relating to land intended for public, affordable or cost-controlled housing. The impact of these measures will be observed over a different timeframe from the PRR, because planning, development and construction take longer than the approval of a new framework.
The next cycle
The main issue now becomes continuity. An exceptional intervention can resolve specific situations and expand the public housing stock, but housing supply requires regular investment. Without multi-year planning, permanent technical teams and maintenance, the end of a financial cycle may create a gap between completed works and new projects ready to proceed.
For municipalities in Lisbon, the South Bank and the Tagus Valley, the PRR experience leaves acquired capacity: developed projects, tested procedures and teams with accumulated knowledge. Preserving that capacity may be as important as securing new funding. Restarting processes and structures with each programme increases costs and extends timescales.
The 31,700 housing solutions should therefore be viewed as a milestone. The target was exceeded, but the need remains. Housing policy now enters a phase in which the quality of management, conservation of the assets created and preparation of the next project pipeline will be decisive in turning exceptional investment into a lasting public structure.
Sources
- Governo de Portugal
05 · Article
Refurbishment sustains work but loses its project pipeline
Urban refurbishment activity increased by only 0.8% in July. In the first half of 2026, 2,960 refurbishment projects were licensed, 12.5% fewer than in the corresponding period.
Positive activity, limited growth
Urban refurbishment indicators remained positive in July 2026, but slowed significantly. The activity level index grew by 0.8% compared with the same month a year earlier, while the order book increased by 6.9%. On average, companies reported 8.7 months of contracted production, slightly below the nine months recorded a year earlier.
Having secured orders provides companies with some stability. The more fragile figure appears upstream. In the first half of the year, 2,960 refurbishment projects were licensed, 12.5% fewer than in the same period of 2025. The reduction was 10.8% for residential buildings and 15.2% for non-residential buildings.
Permit statistics do not cover every intervention because certain works may not be subject to the same type of prior municipal control. Even so, the trend suggests a slower inflow of new formal projects at a time when much of the building stock requires functional, energy-efficiency and structural upgrades.
Refurbishment means creating supply from existing buildings
Refurbishment does not entirely replace new construction, but it makes it possible to recover vacant buildings, adapt housing types and extend the useful life of existing structures and embodied materials. In established urban centres, it is also one of the few ways to increase residential use without consuming new land.
The process does, however, involve specific uncertainties. The actual condition of a building may become apparent only during the work. Heritage, accessibility, fire safety, acoustics and thermal performance require complex coordination. When material and labour costs are rising, this uncertainty makes it more difficult to finalise budgets and secure financing.
The reduction in permits may also reflect owners postponing decisions, investors reassessing viability or longer municipal processes. Each cause requires a different response. Simplifying procedures is no substitute for design and inspection; encouraging investment does not remove the need for quality standards; conserving heritage does not mean preventing adaptation to new uses.
Avoiding a future decline
The difference between the current order book and recent permit levels warrants monitoring. Companies may sustain activity through contracts already signed while the number of projects feeding the following months declines. If the trend persists, the slowdown may become more visible after current work is completed.
For Lisbon and the urban centres of the South Bank and the Tagus Valley, refurbishment remains a policy for housing, the environment and urban quality. Its importance should not be measured solely by the volume of work. Each restored building can bring use back to a street, reduce consumption, preserve resources and prevent unnecessary expansion. The challenge is to create sufficient predictability for this work to take place without reducing technical standards.
Sources
- Vida Imobiliária
- Instituto Nacional de Estatística (INE)
06 · Article
Affordable rent: concrete responses, limited scale
Lisbon opened an extraordinary competition for 25 homes intended for young people aged up to 35. In Seixal, 24 validated applications took part in the draw for 12 municipal properties.
Two competitions, 37 homes
In the summer of 2026, Lisbon opened an extraordinary competition under the Affordable Rent Programme to allocate 25 homes, ranging from studios to three-bedroom properties. The initiative, called “Back to the Neighbourhood”, set specific requirements for young people aged up to 35. The homes were financed through municipal funds, the 1.º Direito Programme or the Recovery and Resilience Plan.
In Seixal, the Affordable Rent Programme placed 12 residential properties into a draw. The public draw took place on 28 August, after 24 applications had been validated. The municipality had accepted applications between 20 July and 18 August.
The two schemes do not have the same administrative structure, but they illustrate a common issue: municipal programmes can produce responses directly related to household incomes and circumstances, although the quantity available remains limited in relation to metropolitan demand.
Scale is also territorial
In Lisbon, reserving homes for young people seeks to address the departure of residents from the neighbourhoods where they grew up or where they retain family and professional networks. Access depends not only on the availability of a below-market rent. It also depends on location, contractual stability and the ability to maintain daily routines without increasing transport costs.
In Seixal, affordable rental provision forms part of residential demand shaped by links with Lisbon and movement within the South Bank itself. The availability of 12 properties is significant for the selected households, but it also highlights the gap between each competition and the scale of need. The existence of two validated applications for each home does not represent all potential demand, because the eligibility requirements and application periods limit the participating group.
Public provision can grow through municipal construction, acquisition, refurbishment or the mobilisation of properties belonging to other entities. Each approach has different timescales and costs. Construction permanently increases the housing stock, but requires land, design and building work. Acquisition may be faster, although it depends on market prices. Refurbishment recovers existing assets, but involves greater technical uncertainty.
Rules and continuity
In 2026, Lisbon also began a procedure to amend the Municipal Right to Housing Regulation, seeking to update the instrument in line with current needs and the framework of municipal policies. Revising the rules is important because access criteria, priorities, documentation and allocation mechanisms determine who is able to participate in the programmes.
The effectiveness of affordable renting will be measured by continuity, not merely by isolated competitions. Regular supply allows families to plan, reduces the concentration of applications and improves transparency regarding available housing stock. The metropolitan scale also requires coordination between municipalities, transport and employment. Lisbon and Seixal demonstrate two local responses; the next challenge is to turn them into a stable network of housing alternatives.
07 · Article
Low carbon reaches the building site
Professional demand for some sustainable solutions is growing faster than for other material categories. In parallel, research is exploring ways to incorporate carbon dioxide into construction products.
From intention to specification
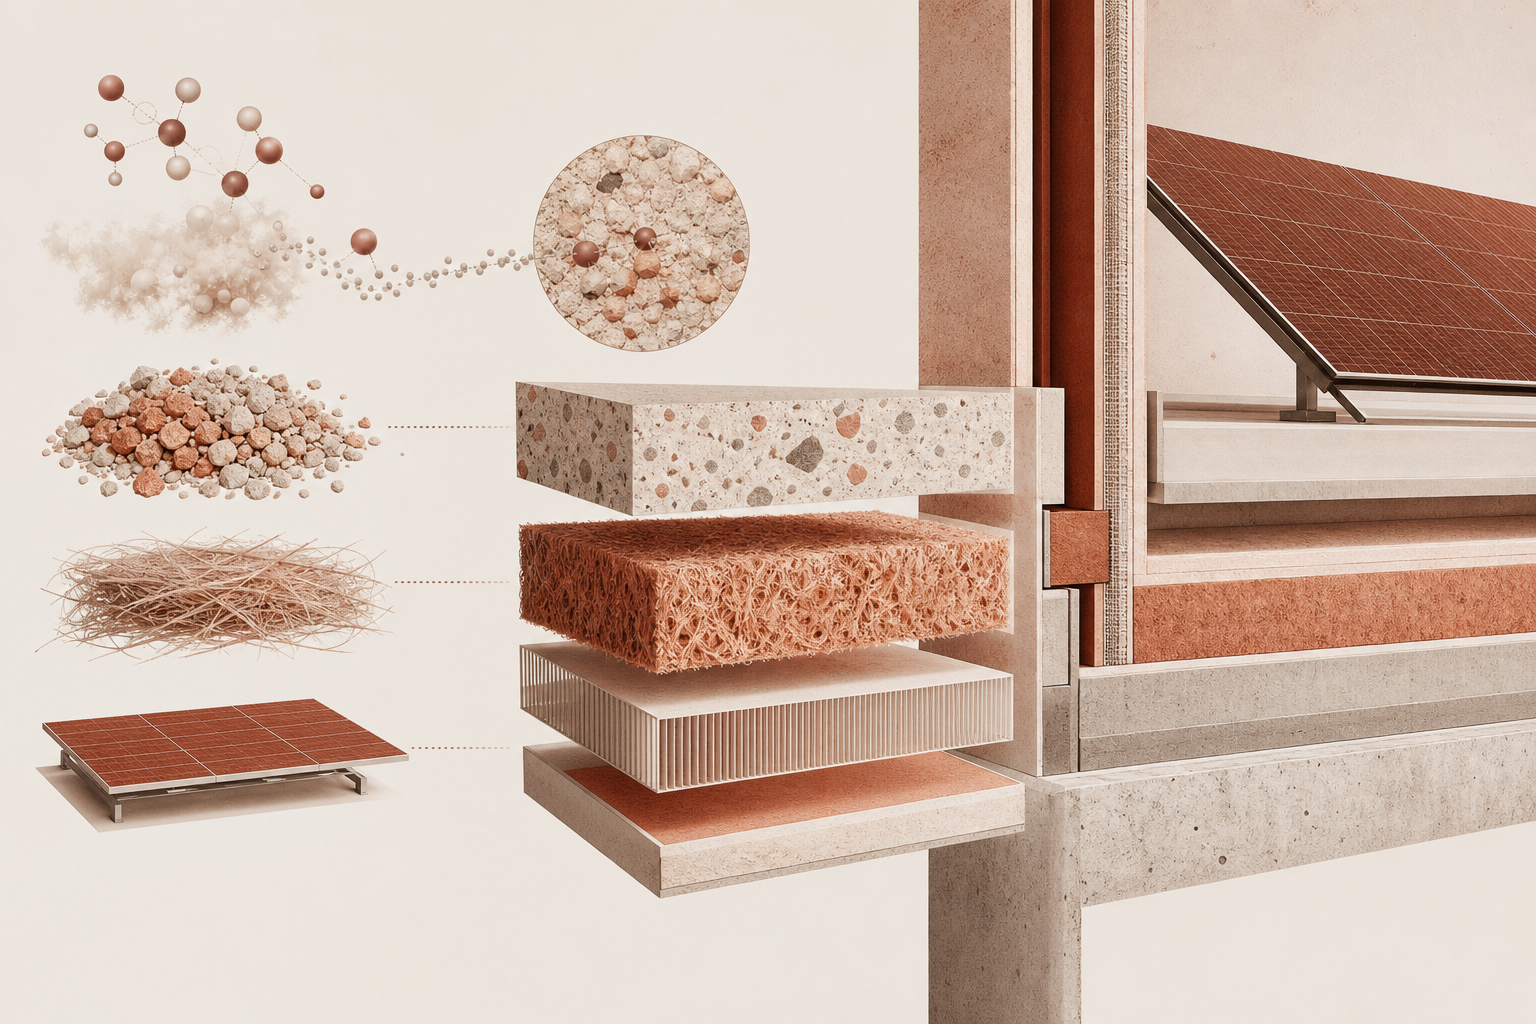
Sustainability in construction is beginning to emerge in routine purchasing and specification decisions. According to data released by a Portuguese materials platform, demand for products considered sustainable is growing at twice the rate of other categories. The most sought-after solutions include photovoltaic modules, solar water-heating systems and high-performance thermal insulation, including rock wool.
The indicator comes from one company and does not represent the entire market. Even so, it identifies a practical change: energy efficiency and local energy generation are no longer confined to flagship projects and are becoming part of residential construction at different scales.
Part of this change results from the need to reduce consumption during use. In a context of rising construction costs, efficient solutions face more rigorous assessment of their initial investment. The decision depends on design quality, installation, the building’s orientation and the time needed to recover the cost through energy savings.
Embodied carbon
Efficiency during use is only one environmental dimension. The production of cement, concrete, steel, ceramics, glass and insulation materials also involves energy consumption and emissions. In July 2026, the National Laboratory for Civil Engineering hosted an international conference in Lisbon dedicated to the mineralisation of carbon dioxide in construction materials and products.
This field investigates processes in which carbon dioxide is used as a resource and fixed within mineral matrices. The aim is to develop materials with a lower climate impact and create uses for captured carbon streams. The transition from research to the building site will depend on verification of performance, safety, durability, cost, standardisation and industrial capacity.
Material innovation should not be assessed solely by the amount of carbon incorporated. A product must perform its construction function for the intended period, allow maintenance and permit replacement or recycling. A solution with a lower initial impact may lose its advantage if it has a shorter service life or requires disproportionate transport and processing.
Building better with less
The transition does not happen only through new products. Reducing the amount of material used, avoiding unnecessary demolition, reusing components, designing adaptable structures and limiting waste can have an immediate effect. In this respect, refurbishing existing buildings is also a resource conservation strategy.
For buyers and investors, environmental performance should be presented through verifiable information: estimated consumption, thermal characteristics, material origins, maintenance and applicable certifications. Generic terms do not make it possible to compare solutions or anticipate costs.
Growing demand for insulation and solar energy shows that the market already recognises part of this value. Research into carbon mineralisation points towards a more profound change in the composition of materials. Between the two lies the work of architects, engineers, manufacturers and builders: turning environmental objectives into durable, repairable buildings suited to their use.
Sources
- Idealista News
- LNEC